There are just 26 days left before the 17 October close of Defra's Mandatory Carbon Reporting consultation.
As I mentioned in a previous blog post, the formal requirements are not particularly detailed. Many of the biggest companies are already reporting their greenhouse gas emissions via the Carbon Disclosure Project
and what is more, Mandatory Carbon Reporting, unlike the EU ETS and
CRC, does not attempt to put a price on carbon or mandate reductions.
So why would Defra go through all the trouble?
In
a phrase, climate change. The British Government made history with its
5-year carbon budgets, which established a path to an 80% emissions
reduction target by 2050.
The most powerful tool in the
Government's current arsenal is the EU Emissions Trading Scheme.
Participating installations are responsible for approximately 48% of the
country's emissions, but the low carbon price reduces incentives to
invest in longer term reduction measures. Similarly, the Carbon
Reduction Commitment Energy Efficiency Scheme (CRC-EE) targets firms
responsible for 10% of the country's emissions but energy represents on
average 3% of these company's costs. For these companies, the £12
carbon price in the CRC is rarely enough to justify massive energy
reduction investments.
Note that the EU ETS and CRC schemes combined do
not cover 58% of the UK footprint due to double counting. Most of the
large companies covered by the CRC purchase energy from ETS compliant
utilities. The ETS works to drive supply side reductions while the CRC
drives demand side reductions. The problem is that those reductions aren't coming fast enough.
Mandatory Carbon Reporting gives
the Government a third arrow for its quiver. According to the latest CDP report, the subset of FTSE 350 companies that voluntarily report their emissions
had a combined Scope 1 and 2 footprint of over 487 million tonnes CO2e
for their worldwide operations. This is remarkably close to the UK's national carbon footprint total of 470 million tonnes CO2e. Broadening this to the 1,000 or more firms
covered under Mandatory Carbon Reporting would give a combined footprint considerably
larger than the entire country. The emissions covered under Mandatory
Carbon Reporting, then, are potentially several times larger than any
other carbon reporting measure in the Government's arsenal.
Here's
where it gets interesting. Defra's Impact Assessment for the draft
Mandatory Carbon Reporting consultation estimates that firms will
achieve a 4% emissions reduction simply by improving their footprint
reporting. In other words, they assume that forcing the Board and
investors to pay attention to the company's footprint will lead to carbon savings, without requiring carbon caps, taxes, or mandated
technology measures. Of course, not all of those global emission reductions can be counted against the UK's carbon budget, but with so many of the largest emitters
covered under Mandatory Carbon Reporting, these "easy" reductions will
make a material contribution to Government carbon saving efforts.
In addition, the current reporting proposal is only the first step. In 2015 Defra will review the programme with an eye to broadening it to cover every large company in the UK, public and private.
And should the need arise for a cap and trade system or carbon tax covering these companies at some point in the future, Defra will already have their emissions data at the ready.
Even though Mandatory Carbon Reporting looks like business as usual at first blush, its wide net makes it a very big deal indeed.
Friday, 21 September 2012
Tuesday, 18 September 2012
Carbon Clear's Autumn Breakfast Briefings: Telling the Story
There are only two days to go before the launch of Carbon Clear's autumn Breakfast Briefing series. A good deal of thought went into these sessions, and I like to think they come together to tell a compelling story. Here's how they fit together.
The first session, on 20 September, will cover the UK Government's new Mandatory Carbon Reporting legislation, which I blogged about a few weeks ago. I'll be joined at that session by my colleague Vincent Reulet and by Mardi McBrien, MD of the Carbon Disclosure Standards Board.
We'll be talking about why the Government is pushing for mandatory carbon reporting, how this new requirement fits in with other carbon reporting efforts like the EU ETS, the Carbon Disclosure Project and the Carbon Reduction Commitment Energy Efficiency Scheme (CRC), and how companies can both comply with this legislation and use it to gain competitive advantage. Should be an informative and dynamic event.
A few weeks later, on 2 October, we will be talking about what I sometimes refer to as Carbon Offsetting 2.0. After the first wave of carbon offsetting in the mid- to late-2000s, there was a lull. Now, a new crop of companies, from Microsoft to Marks & Spencer, are announcing carbon neutrality programmes. We'll be discussing how this new round of carbon offsetting differs from the first, and how other companies can benefit.
Then, on 17 October we will be unveiling our Carbon Maturity whitepaper. Our crack team of consultants has pooled decades of accumulated experience working with over a hundred companies to develop a model of corporate carbon maturity. We've found that companies at each stage of the maturity curve share certain characteristics and encounter similar obstacles before moving on to the next level. This applies to both their internal carbon management activities and their carbon offsetting initiatives. Delegates at this briefing will learn how the carbon maturity model works, and how to benchmark their companies' performance against other businesses.
The breakfast briefing series, then, tells a story. We start with carbon footprinting and show how it can go from being a burden to a source of competitive advantage. We then move on to carbon offsetting and show how it has evolved to become a source of real business value for the largest companies. And then we describe how companies around the world are developing increasingly sophisticated carbon management programmes that deliver benefits for management, employees, investors and the wider community.
I think that's a story that every company should hear. Join us, and help tell the story.
The first session, on 20 September, will cover the UK Government's new Mandatory Carbon Reporting legislation, which I blogged about a few weeks ago. I'll be joined at that session by my colleague Vincent Reulet and by Mardi McBrien, MD of the Carbon Disclosure Standards Board.
We'll be talking about why the Government is pushing for mandatory carbon reporting, how this new requirement fits in with other carbon reporting efforts like the EU ETS, the Carbon Disclosure Project and the Carbon Reduction Commitment Energy Efficiency Scheme (CRC), and how companies can both comply with this legislation and use it to gain competitive advantage. Should be an informative and dynamic event.
A few weeks later, on 2 October, we will be talking about what I sometimes refer to as Carbon Offsetting 2.0. After the first wave of carbon offsetting in the mid- to late-2000s, there was a lull. Now, a new crop of companies, from Microsoft to Marks & Spencer, are announcing carbon neutrality programmes. We'll be discussing how this new round of carbon offsetting differs from the first, and how other companies can benefit.
Then, on 17 October we will be unveiling our Carbon Maturity whitepaper. Our crack team of consultants has pooled decades of accumulated experience working with over a hundred companies to develop a model of corporate carbon maturity. We've found that companies at each stage of the maturity curve share certain characteristics and encounter similar obstacles before moving on to the next level. This applies to both their internal carbon management activities and their carbon offsetting initiatives. Delegates at this briefing will learn how the carbon maturity model works, and how to benchmark their companies' performance against other businesses.
The breakfast briefing series, then, tells a story. We start with carbon footprinting and show how it can go from being a burden to a source of competitive advantage. We then move on to carbon offsetting and show how it has evolved to become a source of real business value for the largest companies. And then we describe how companies around the world are developing increasingly sophisticated carbon management programmes that deliver benefits for management, employees, investors and the wider community.
I think that's a story that every company should hear. Join us, and help tell the story.
Thursday, 13 September 2012
Who's Afraid of Low Carbon Prices? Part 3: Not Australia
Last week I attended a briefing at the Australian High Commission in London. The Victorian Government (the Australian state, not the 19th century ruler) hosted a session for carbon market participants to present the latest updates to the country's ambitious greenhouse gas cap-and-trade scheme.
The Australian carbon pricing initiative begins as a straightforward carbon tax, set at A$23 (€19), indexed to inflation and payable by the largest 500 or so industrial polluters. European carbon allowances, by contrast, were trading below €8 yesterday. That price difference initially attracted howls of protest from industry lobbyists.
From July 2015, however, Australia switches from a carbon tax to a cap-and-trade scheme linked to the EU-ETS. That means Australian companies will be able to buy European credits (EUAs), and to an extent UN-issued CERs to comply with up to 50% of their carbon reduction obligations. Similarly, Europeans will be able to buy Australian Allowances to satisfy EU abatement requirements.
The EU-Australia linkup is not a marriage of equals, however. The EU is directly responsible for 11% of global greenhouse gas emissions, while Australia emits just 1.5% of the global total - about the same as the United Kingdom. The additional supply of relatively cheap EU allowances is expected to dwarf the additional demand for allowances generated by Australia's emissions-intensive firms. If the business-as-usual EUA price remained at €8 in 2015 and all else being equal, we should expect the carbon price for the linked systems to equalise much closer to the EUA price - somewhere around €9.30.
This analysis indicates that linking the two carbon trading schemes might cut the Australian carbon price in half. In reality, the EU expects the carbon price to rise by 2015, but still much lower than the Australian carbon tax level. Isn't that bad news for Australia? Surely we need high carbon prices to drive emission reductions?
That might be true if the Australians had magically built a dome over their country and were the only people affected by the carbon emissions. The reality is that Australia's greenhouse gas emissions contribute to climate change across the planet. Similarly, the CO2 from a Polish or American power station adds to the global atmospheric buildup contributing to droughts and flooding in Australia.
Global atmospheric circulation means that an emission reduction anywhere helps the climate everywhere and vice versa. If we need to save 1 million or 1 billion tonnes of CO2, it doesn't matter too much where that savings happens. What is important for climate change is that this savings happens sooner rather than later.
As I discussed in an earlier blog post, the emissions trading scheme is a price discovery mechanism that helps us identify the most cost effective emissions reduction opportunities across the entire scheme. So a relatively low carbon price for a combined Australia-EU trading systems means there are significant opportunities to reduce green house gas emissions with minimal economic impact. It means the Australian Government can make its contribution to curbing global climate change even cheaper and faster than before. The market can work, and that's a good news story.
It also means that there are still major carbon reduction opportunities that we (including Australia) are not pursuing. And that's bad news. One analysis says that global greenhouse gas emissions need to peak by 2015 and then decline year on year if we are to limit average global temperature increases to a damaging but not wholly catastrophic 2 degrees. A low carbon price means we continue to fight this battle with one arm tied behind our collective back. It means governments are still failing to set sufficiently ambitious targets to set us on a path towards a low-carbon future.
The Australian carbon pricing initiative begins as a straightforward carbon tax, set at A$23 (€19), indexed to inflation and payable by the largest 500 or so industrial polluters. European carbon allowances, by contrast, were trading below €8 yesterday. That price difference initially attracted howls of protest from industry lobbyists.
From July 2015, however, Australia switches from a carbon tax to a cap-and-trade scheme linked to the EU-ETS. That means Australian companies will be able to buy European credits (EUAs), and to an extent UN-issued CERs to comply with up to 50% of their carbon reduction obligations. Similarly, Europeans will be able to buy Australian Allowances to satisfy EU abatement requirements.
The EU-Australia linkup is not a marriage of equals, however. The EU is directly responsible for 11% of global greenhouse gas emissions, while Australia emits just 1.5% of the global total - about the same as the United Kingdom. The additional supply of relatively cheap EU allowances is expected to dwarf the additional demand for allowances generated by Australia's emissions-intensive firms. If the business-as-usual EUA price remained at €8 in 2015 and all else being equal, we should expect the carbon price for the linked systems to equalise much closer to the EUA price - somewhere around €9.30.
This analysis indicates that linking the two carbon trading schemes might cut the Australian carbon price in half. In reality, the EU expects the carbon price to rise by 2015, but still much lower than the Australian carbon tax level. Isn't that bad news for Australia? Surely we need high carbon prices to drive emission reductions?
That might be true if the Australians had magically built a dome over their country and were the only people affected by the carbon emissions. The reality is that Australia's greenhouse gas emissions contribute to climate change across the planet. Similarly, the CO2 from a Polish or American power station adds to the global atmospheric buildup contributing to droughts and flooding in Australia.
Global atmospheric circulation means that an emission reduction anywhere helps the climate everywhere and vice versa. If we need to save 1 million or 1 billion tonnes of CO2, it doesn't matter too much where that savings happens. What is important for climate change is that this savings happens sooner rather than later.
As I discussed in an earlier blog post, the emissions trading scheme is a price discovery mechanism that helps us identify the most cost effective emissions reduction opportunities across the entire scheme. So a relatively low carbon price for a combined Australia-EU trading systems means there are significant opportunities to reduce green house gas emissions with minimal economic impact. It means the Australian Government can make its contribution to curbing global climate change even cheaper and faster than before. The market can work, and that's a good news story.
It also means that there are still major carbon reduction opportunities that we (including Australia) are not pursuing. And that's bad news. One analysis says that global greenhouse gas emissions need to peak by 2015 and then decline year on year if we are to limit average global temperature increases to a damaging but not wholly catastrophic 2 degrees. A low carbon price means we continue to fight this battle with one arm tied behind our collective back. It means governments are still failing to set sufficiently ambitious targets to set us on a path towards a low-carbon future.
Monday, 13 August 2012
What Defra's Greenhouse Gas Reporting Consultation Won't Tell You
In late July I tweeted the news that the UK Department for Food, Environment and Rural Affairs (DEFRA) has released the final consultation on its proposed mandatory carbon reporting legislation.
If you went to Defra's website and download the consultation documents following that announcement, you might have felt somewhat confused and more than a little disappointed. It all feels rather vague.
The draft consultation document from late last year, and Defra's ensuing feedback document released this spring each ran to dozens of pages focusing on the technical minutiae of setting organisational footprint boundaries based on operational versus financial control, whether or not to include Scope 3 emissions in the footprint, and the pros and cons of reporting all six Kyoto categories of greenhouse gases. In the end, Defra expressed strong views on how these and other points should be addressed, and went to some length to justify those decisions.
The final consultation document totals just six pages and lacks specificity on most of these important points. Required reporting standard? Not specified. Financial versus operational control? Not clearly specified. Penalties for non-compliance? Silence. What is more, the final consultation document appears to change the inclusion criteria that determine which companies are covered under the proposed legislation, narrowing them in one regard and substantially broadening them in others. You can find Defra's greenhouse gas reporting consultation page here - as I said, it's a relatively quick read.
When Nick Clegg announced the introduction of mandatory carbon reporting at the Rio+20 summit, it was touted as proof that the UK was leading the world in its response to climate change. So why the sudden absence of detail? I have three theories.
The first is political. The initial consultation documents clearly were written by technical specialists, who were focused on getting things right. The final legislation needs to be read into the House of Commons and debated by politicians. The more detail is included, the more likely the legislation will get delayed due to time pressure or tripped up by a Member of Parliament who objects to one or more provisions. Seen from this perspective, short and sweet is the way to go. Perhaps Defra will choose to issue clarifications containing the detail once the legislation is passed.
The second potential reason for this approach is to maximise the number of companies who report. I call this the "boiled frog" approach. By refusing to define rigidly what companies must report and how they must report it, Defra might be making it easier to comply. Given the choice between companies submitting poor quality or incomparable data versus no data at all, my preference would be to get poor quality data. After all, we know the footprint isn't zero, and this flawed initial number gives us something with which to start. Defra can then issue additional guidance as time goes on to improve the quality of data that companies submit and ensure that it becomes easier to make comparisons between companies or industry sectors. The responding companies, meanwhile, can gradually begin to implement better data collection and quality assurance systems - perhaps with less internal resistance than if they tried to jump from no carbon reporting to industry best practice all at once.
And the third potential reason Defra may have chosen to keep it simple, is that many of the largest companies already report their carbon footprints in a reasonably consistent way via the Carbon Disclosure Project. CDP respondents report their greenhouse gas emissions using ISO 14064 or the GHG Protocol and answer the same standard questions about their carbon footprints. Carbon Clear is a CDP accredited Consultancy Partner, and while respondents' footprints are not directly comparable, they do tend to take a similar approach. I expect UK listed firms that already report their emissions to comprise the bulk of the total footprint covered under the Government's mandatory carbon reporting scheme. As a result, Defra may have decided they did not need to reinvent the wheel.
The real reason is likely to include some of each of these, and perhaps some others that never see the light of day. Whatever the reason, the result in the short term is confusion for firms that don't yet know whether they will be included, nor what they need to report. Based on our previous conversations with Defra and the CDP, our team at Carbon Clear is able to tease some extra detail out of the current legislative draft, and will aim to give our clients a head start in preparing for the advent of mandatory carbon reporting in the UK.
Thursday, 9 August 2012
Science: It Works on Mars and on Earth
On Sunday the NASA Mars Science Laboratory rover, nicknamed Curiosity, landed on the Red Planet and began beaming pictures home. This isn't a space exploration blog, but I'll explain the relevance in a moment.
As you might imagine, landing a 900-kilogram, six-wheeled, plutonium powered robot car on another planet is not easy. In fact, this was the most difficult and complex Mars landing attempt to date. Let's run through the main challenges:
1. Build a plutonium-powered robot vehicle than can operate semi-autonomously for an entire year, tolerate sub-freezing temperatures, radiation, dust storms and the vacuum of space.
2. Fit that vehicle into the nose cone of a 58-meter rocket, fill that rocket with an explosive mix of kerosene and liquid oxygen, aim it at the point in space where you expect Mars to be in eight months' time and fire it off.
3. Eight months later, drop the space capsule into the Martian atmosphere at 20,000 kilometers per hour. If it enters at too steep an angle it will burn up; too shallow and it will skip away and be lost in space. It's now 154 million miles away - too far for mission controllers to steer it in real time, so you will have to have made the capsule smart enough to make its own high-speed course adjustments.
4. Once the capsule has slowed from to only a thousand miles and hour, jettison the heat shield and pop open a parachute. This will slow it even more. Again, the capsule is too far away for humans to control directly, so this has to happen automatically.
5. Once the capsule is 1.1 miles off the ground, fire the eight retro-rockets on the descent vehicle. These will steer the lander and bring the whole SUV-sized assembly to a hover over the surface of Mars. Yes, this has to happen autonomously, too.
6. Once the assembly is hovering on its retro-rockets, lower the robot car gently to the surface on a 7.5 meter nylon cable. When the car has touched down, cut the cord and fly the rocket assembly off to crash a safe distance away.
7. If the vehicle is okay, it will begin sending photographs to Earth. The signals will go from the rover to a space observatory that has been orbiting Mars for the past six years. That orbiter will then bounce the signal off another orbiter that has been circling Mars for ten years in order to reach Earth! The mission controllers on Earth will find out fourteen minutes later whether it all worked.
And amazingly, it all worked! The Curiosity rover is sitting safely on the surface of Mars and Scientists and engineers are celebrating a trove of exciting photos and video footage.
The successful Curiosity landing was a triumph of science and engineering. We can use these tools to make accurate predictions about a long chain of complex events. And we can use our knowledge and ability to achieve complex and ambitious goals.
Here on Earth, few goals are as complex and ambitious as tackling climate change. But the science is unambiguous. We know what is causing climate change and we know that greenhouse gas emissions need to drop. We even know what emission sources to address and already have the tools to do it. Reducing greenhouse gas emissions to safe levels doesn't require any new technological advances or scientific inventions. Existing clean energy, energy efficiency, resource efficiency and forest management systems can do it. Renewable energy use is soaring across the world, major carmakers are bringing high-efficiency hybrid cars to market, and ever-larger forest protection projects are being launched in Asia, Africa and Latin America. We know what to do and how to do it, but we're not yet doing it fast enough.
It is clear that governments can't get us there on their own. Politicians' incentive structures make it difficult to make major changes to the built environment and to our energy, transportation and agricultural systems. Governments have an important role to play in promoting transparency, overcoming market distortions, and ensuring a level playing field, but when government is slow to act individuals, communities, civil society and businesses should not hesitate to get involved.
Around the world, companies are switching to renewable energy and improving efficiency, restructuring supply chains to reduce their carbon footprint and save money, and investing in innovative emission reduction projects that help people in the developing world make the transition to a low-carbon future.
Compared to landing a one-tonne rover on Mars, the scientific challenges preventing us from tackling climate change look almost easy. And the Curiosity rover is there, showing us what we can accomplish when we have the determination.
Labels:
carbon emissions,
climate change,
science,
solutions
Tuesday, 24 July 2012
Carbon Clear Job Posting: Interim Communications Manager
We're recruiting! Do you know a talented Communications Manager who's passionate about helping companies tackle climate change?
Due to an anticipated staff vacancy we are looking for an experienced Communications Manager to help us share our experience and successes with our customers. The Interim Communications Manager has day to day responsibility for presenting Carbon Clear to the world via the internet, printed materials, and at relevant industry events.
Learn more on our Careers Page: http://carbon-clear.com/uk/about_us/careers.
(Update one year later: Thanks to those who responded. The role has been filled now and we're delighted to have a permanent Communications Manager on the team.)
Due to an anticipated staff vacancy we are looking for an experienced Communications Manager to help us share our experience and successes with our customers. The Interim Communications Manager has day to day responsibility for presenting Carbon Clear to the world via the internet, printed materials, and at relevant industry events.
Learn more on our Careers Page: http://carbon-clear.com/uk/about_us/careers.
(Update one year later: Thanks to those who responded. The role has been filled now and we're delighted to have a permanent Communications Manager on the team.)
Thursday, 5 July 2012
Going Mainstream
This is interesting:
At Carbon Clear, we've been saying this for years, but nice to see this mantra make the cover of CFO Magazine. (Hat tip: @greenmondaynews)
Labels:
business,
corporate brand image,
economics,
FTSE,
philosophy,
solutions,
sustainability
U.S. Heatwaves: "Weather" versus "Climate"
It's summer, and that means it's time for another round of record-breaking heatwaves in the United States.The heatwave of the past week has triggered forest fires across the western states. Washington, DC staggered under 104-degree (F) temperatures - the air conditioner load helped prolong a five-day blackout across the eastern states. Back in the 1990s aid agencies used photos of the earth at night to flag underdeveloped countries where people had to live without electricity. I never thought I'd see those types of images for the suburbs of Baltimore and Washington DC:
![]() |
| Washington-Baltimore on June 28, 2012 |
![]() |
| A less brightly-lit Washington-Baltimore on June 30, 2012 |
We might define "weather" as the meteorological conditions when you look out the window. Is it raining? Is it hot? Weather varies day by day, and it's difficult to predict more than a week in advance. "Climate" refers to the typical conditions we might expect at a given time of year. San Francisco is normally foggy on summer afternoons, Montana is typically frigid in winter. A freak storm or unexpected heat wave is bad weather. Searing temperatures every summer, year in and year out - that sounds more like climate. If that's not the climate we used to have, then it would be fair to say that the climate is changing.
Climate scientists are generally careful not to attribute any particular weather event to climate change. Their models of overall change are predictions of longer-term trends. But the weather we're seeing is beginning to match those predictions. How long before "longer term" becomes "now"?
Labels:
climate change,
impacts,
philosophy,
science,
sustainability
Posting Resumes: Mandatory Carbon Reporting and More
It's been a busy few weeks and I have built up a backlog of stories about which to blog. I'll try to make up for it with a series of short posts about some of the more interesting stories of the past month, including air conditioners in the developing world, mandatory carbon reporting in the UK, ocean acidification, the Vauxhall Ampera, and yet another series of heat waves in the US. Stay tuned!
Monday, 18 June 2012
Tweeting Against Fossil Fuel Subsidies is Fine, but...
There is a 24-hour "Twitterstorm" currently running to mark the Rio+20 environmental conference in Brazil. The #EndFossilFuelSubsidies tweet-a-thon is being organised by environmental group 350.org, to help push the issue onto the agenda of world leaders attending the conference.
The logic behind the campaign is obvious: fossil fuel combustion is the single largest source of man-made greenhouse gas emissions. We burn excessive fossil fuels in part because we fail to factor their environmental impact into the price. Carbon taxes and cap-and-trade schemes are intended to help send more accurate (higher) price signals and thereby reduce demand. However, not only are we failing to implement aggressive carbon pricing schemes, nations around the world actually offer billions of dollars of subsidies that lower the price of fossil fuel production and consumption. Other subsidies are non-financial: relaxing environmental restrictions in protected areas reduces compliance costs for fossil fuel producers, making it easier to increase supply at a given price.
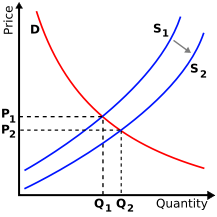
What would compel otherwise rational decision makers to support such an illogical policy? In a nutshell, it's a lack of joined up thinking. Why subsidise fossil fuel production? To shift the supply curve out to the right - increasing supply, reducing price, or both, as seen below:
Why do we need to increase supply? Because we are consuming increasing quantities of fossil fuels. Why are we consuming so much? Because we are not using renewables. Because our buildings are inefficient, and we travel long distances in inefficient vehicles, and we manufacture large quantities of products in inefficient factories.
Why subsidise fossil fuel consumption? Because otherwise influential voters would revolt, poorer members of society would face fuel poverty, and manufacturers would threaten to take jobs elsewhere. Why are voters, households and employers sensitive to the price of fuel? Because their homes, vehicles and buildings use energy inefficiently and because they do not generate much, if any, of their own local power.
In other words, when confronted with the challenge of people using energy wastefully and failing to use locally available renewables, national leaders have responded with subsidies that boost production and lower the price of fossil fuels! You can see how policy makers might find this response rational on a case-by-case basis, but from a broader systems perspective the case for these subsidies becomes ludicrous. This "solution" becomes even more appalling when one considers the environmental cost.
A "big-picture" systems view can tackle these challenges simultaneously from an economy-wide and a local level. If it is too expensive to drive vehicles long distances when people must face the full cost of fuel, then we can find ways to reduce vehicle miles per person or per tonne of goods: putting homes or factories closer to offices, increasing fuel efficiency, and using mass transit to reduce the number of cars people need to own. If fuel costs are making homes unaffordable and businesses uncompetitive, then we can find ways to get the same benefits with less fuel: switch to renewables, where the "fuel" (sunlight, wind, etc) is free; or improve building and appliance efficiency so less energy is wasted.
#EndFossilFuelSubsidies is a clever campaign, but we need more systems-level thinking if it is to become more than a slogan that disappears after 24 hours.
Sunday, 3 June 2012
Small but Mighty: The 2012 State of the Voluntary Carbon Market Report
The State of the Voluntary Carbon Markets 2012 report was launched yesterday at Carbon Expo in Cologne, Germany. The Ecosystem Marketplace team has done a tremendous job, reaching across the industry to collect masses of data on carbon project transactions by project type, standard, geography, and a host of other criteria, and then slicing and dicing this data to tell a coherent story about supply, demand, and buyer behavior.
Analysts, investors, and project developers rely on the State of report to help them make informed decisions and grow the market. This is an extremely valuable service, and somewhat surprisingly, Ecosystem Marketplace provides all this information free of charge via their website. It's a public service, and a valuable one. Carbon Clear is a proud sponsor of the report. Just one more way we contribute to the low-carbon economy.
A key finding from this year's report is that the voluntary carbon market has continued to grow strongly, even in the midst of an international economic and financial crisis. In fact, 2011 was the best year ever in terms of over-the-counter transactions. Excluding one very unusual 2010 transaction on the now-defunct CCX system, carbon credit sales volumes rose 28% in 2011, and the average price per tonne rose, too.
In many ways, the launch of the 2012 report marked the coming of age of the voluntary carbon market. The organisers of Carbon Expo operate mainly in the compliance market, focusing on carbon credits from the Clean Development Mechanism and EU Emission Trading Scheme (EU ETS). With thousands of industrial emitters covered under the EU Emission Trading Scheme (ETS) and scores of brokers and investment banks transferring credits back and forth, the compliance market is well over a hundred times larger than the voluntary one. To an outsider, a Carbon Expo session focused on the voluntary market would seem a side show, unlikely to be of interest to the majority of delegates. In the event, Ecosystem Marketplace was allocated a small room away from the main hall in which to launch their report on the voluntary market. They didn't even have a microphone.
And then something quite unexpected happened. The main hall of Carbon Expo sat half-empty, while delegates flocked to Meeting Room 2 to listen to Molly Peters-Stanley and the rest of the panel. They filled every seat, sat on the floor, stood against the walls and spilled out into the corridor beyond to hear the latest news on the voluntary market. There were nearly as many people standing outside as managed to make their way in. In the photo below you can just make out the throngs in the hallway craning their necks to see into the room.
Why such a big crowd to hear about a relatively small market?
The voluntary market has an importance and influence that belies its size. First, it has been a source of experimentation and innovation that has shown time and again how carbon finance can deliver clear livelihoods benefits to families and communities in developing countries. Voluntary carbon projects are often more effective at channeling resources into pro-poor initiatives like improved cook stoves and safe drinking water. Many methodological innovations, like sampling-based monitoring and "suppressed demand" started in the voluntary carbon credit standards and have subsequently found their way into the much larger UN-backed Clean Development Mechanism. So the voluntary market can help compliance market players get a taste of what's coming next.
Second, and importantly, the voluntary market continues to experience fundamental growth even in difficult economic times. It has provided one of the only consistent sources of good news fight against climate change. As I discussed in an earlier blog post, the factors that affect buying decisions in the voluntary carbon market are quite different from those that drive most compliance credit purchasers. In the past it may have been easy for some observers to assume that voluntary market credits were "second best" - an unconsidered approach would be to assume verified emission reductions (VERs) were inferior because they sat outside the U.N. regulated system, and therefore that customers bought them only because they were less expensive than compliance credits.
That view would have been wrong. The reality is that VERs are not inferior, just different. Depending on your criteria, they may often be superior. And these different characteristics result in different market outcomes. Over the past year, many types of voluntary credits have held their value while CDM credit prices (CERs) are in free-fall. The growth paths of these two markets are diverging as well. While the total value of CDM transactions grew as a result of investor hedging and arbitrage strategies, both the volume and average price of over-the-counter VERs rose as a result of continued strong demand, leading to a 29% rise in market value, according to Ecosystem Marketplace. The decoupling of compliance and voluntary credit market behavior demonstrates that the voluntary market increasingly is able to stand on its own. Delegates at Carbon Expo sensed this, even before the results of the State of the Market survey were released.
The State of the Voluntary Carbon Markets 2012 report is packed with enough tables and graphs to satisfy any data junkie. Go read it yourself. After all, it's free.
But if you want only one take-away from the reams of data in the report, it is this: the voluntary market has stepped out of the shadow of the compliance market, and more and more companies recognise the benefits of using voluntary offset credits as part of their carbon reduction initiatives.
The Carbon Clear team is already busy digesting the detailed data from the report. We'd be delighted to share our analysis, and look forward to hearing from you.
Analysts, investors, and project developers rely on the State of report to help them make informed decisions and grow the market. This is an extremely valuable service, and somewhat surprisingly, Ecosystem Marketplace provides all this information free of charge via their website. It's a public service, and a valuable one. Carbon Clear is a proud sponsor of the report. Just one more way we contribute to the low-carbon economy.
A key finding from this year's report is that the voluntary carbon market has continued to grow strongly, even in the midst of an international economic and financial crisis. In fact, 2011 was the best year ever in terms of over-the-counter transactions. Excluding one very unusual 2010 transaction on the now-defunct CCX system, carbon credit sales volumes rose 28% in 2011, and the average price per tonne rose, too.
In many ways, the launch of the 2012 report marked the coming of age of the voluntary carbon market. The organisers of Carbon Expo operate mainly in the compliance market, focusing on carbon credits from the Clean Development Mechanism and EU Emission Trading Scheme (EU ETS). With thousands of industrial emitters covered under the EU Emission Trading Scheme (ETS) and scores of brokers and investment banks transferring credits back and forth, the compliance market is well over a hundred times larger than the voluntary one. To an outsider, a Carbon Expo session focused on the voluntary market would seem a side show, unlikely to be of interest to the majority of delegates. In the event, Ecosystem Marketplace was allocated a small room away from the main hall in which to launch their report on the voluntary market. They didn't even have a microphone.
And then something quite unexpected happened. The main hall of Carbon Expo sat half-empty, while delegates flocked to Meeting Room 2 to listen to Molly Peters-Stanley and the rest of the panel. They filled every seat, sat on the floor, stood against the walls and spilled out into the corridor beyond to hear the latest news on the voluntary market. There were nearly as many people standing outside as managed to make their way in. In the photo below you can just make out the throngs in the hallway craning their necks to see into the room.
Why such a big crowd to hear about a relatively small market?
The voluntary market has an importance and influence that belies its size. First, it has been a source of experimentation and innovation that has shown time and again how carbon finance can deliver clear livelihoods benefits to families and communities in developing countries. Voluntary carbon projects are often more effective at channeling resources into pro-poor initiatives like improved cook stoves and safe drinking water. Many methodological innovations, like sampling-based monitoring and "suppressed demand" started in the voluntary carbon credit standards and have subsequently found their way into the much larger UN-backed Clean Development Mechanism. So the voluntary market can help compliance market players get a taste of what's coming next.
Second, and importantly, the voluntary market continues to experience fundamental growth even in difficult economic times. It has provided one of the only consistent sources of good news fight against climate change. As I discussed in an earlier blog post, the factors that affect buying decisions in the voluntary carbon market are quite different from those that drive most compliance credit purchasers. In the past it may have been easy for some observers to assume that voluntary market credits were "second best" - an unconsidered approach would be to assume verified emission reductions (VERs) were inferior because they sat outside the U.N. regulated system, and therefore that customers bought them only because they were less expensive than compliance credits.
That view would have been wrong. The reality is that VERs are not inferior, just different. Depending on your criteria, they may often be superior. And these different characteristics result in different market outcomes. Over the past year, many types of voluntary credits have held their value while CDM credit prices (CERs) are in free-fall. The growth paths of these two markets are diverging as well. While the total value of CDM transactions grew as a result of investor hedging and arbitrage strategies, both the volume and average price of over-the-counter VERs rose as a result of continued strong demand, leading to a 29% rise in market value, according to Ecosystem Marketplace. The decoupling of compliance and voluntary credit market behavior demonstrates that the voluntary market increasingly is able to stand on its own. Delegates at Carbon Expo sensed this, even before the results of the State of the Market survey were released.
The State of the Voluntary Carbon Markets 2012 report is packed with enough tables and graphs to satisfy any data junkie. Go read it yourself. After all, it's free.
But if you want only one take-away from the reams of data in the report, it is this: the voluntary market has stepped out of the shadow of the compliance market, and more and more companies recognise the benefits of using voluntary offset credits as part of their carbon reduction initiatives.
The Carbon Clear team is already busy digesting the detailed data from the report. We'd be delighted to share our analysis, and look forward to hearing from you.
Wednesday, 23 May 2012
Carbon Expo, the Facilities Show and Sustainability Live!
Event season is well and truly upon us. In mid-May the Carbon Clear team hits the road to appear at environmental and business conferences and exhibitions across Europe. Three major events in three weeks and today is the halfway point.
Last week Shefali Modi, the head of our carbon reduction team, gave a talk at the Facilities Show at NEC Birmingham. The Facilities Show is the biggest facilities management exhibition in the UK. For a group of professionals who focus everyday on how businesses respond to climate change, this was a can't-miss opportunity. Addressing the built environment may be our single greatest lever in our efforts to tackle climate change. From concrete (carbon emissions from cement kilns) and timber (deforestation), to energy and refrigerant use, to the provision of parking and bike storage areas, the decisions we make about buildings and facilities will drive much of our response to climate change.
Shefali spoke about "Carbon Management in Practice" to a packed house as part of the show's 'Sustainable FM Academy'. Later she participated in a panel debate called "The Great Energy Discussion". It's always great to reach out to such an important sector, and we look forward to continuing the many conversations that begun during the event.
This week, a team of our best and brightest are exhibiting at Sustainability Live! (the exclamation point is part of the name, but we'd be excited anyway). Sustainability Live! is the UK's leading water, energy, environmental, land and sustainable business exhibition and we started going years ago. For us, this is a great opportunity to meet old and new business contacts, learn about the latest developments from other service and product providers in the industry, and of course get everyone excited about the benefits we provide to companies looking to transform their relationship to carbon.
If you're at Sustainability Live! this week you can find us on stand S15.
Next week, from 30th May - 1st June, I'll be in Koln (aka Cologne), Germany with some of my colleagues to attend Carbon Expo 2012. Carbon Expo is the big daddy of business-focused climate change conferences. This year it is taking place just down the road (figuratively speaking) and one week after the policy-focused (and controversy-filled) United Nations Bonn Climate Change Conference. The policy decisions resulting from the Bonn Conference will ultimately affect companies that participate in the EU ETS, the evolution of compliance markets in other countries, and the voluntary carbon market. As a result, I expect some lively discussions at Koln in the wake of that event!
Carbon Clear is a major sponsor of the 2012 State of the Voluntary Carbon Market report, published annually by Ecosystem Marketplace. "The State of" report is the most widely read voluntary carbon market publication and the 2012 edition will be launched at Carbon Expo on May 31. We'll be there for the side event marking the launch, and will have copies of this important report available on our stand immediately after the launch.
You can find us at Carbon Expo on stand B057.
If you're attending any of these events, be sure to come over and visit us. If not, you can always contact our team via the Carbon Clear website.
Last week Shefali Modi, the head of our carbon reduction team, gave a talk at the Facilities Show at NEC Birmingham. The Facilities Show is the biggest facilities management exhibition in the UK. For a group of professionals who focus everyday on how businesses respond to climate change, this was a can't-miss opportunity. Addressing the built environment may be our single greatest lever in our efforts to tackle climate change. From concrete (carbon emissions from cement kilns) and timber (deforestation), to energy and refrigerant use, to the provision of parking and bike storage areas, the decisions we make about buildings and facilities will drive much of our response to climate change.
Shefali spoke about "Carbon Management in Practice" to a packed house as part of the show's 'Sustainable FM Academy'. Later she participated in a panel debate called "The Great Energy Discussion". It's always great to reach out to such an important sector, and we look forward to continuing the many conversations that begun during the event.
This week, a team of our best and brightest are exhibiting at Sustainability Live! (the exclamation point is part of the name, but we'd be excited anyway). Sustainability Live! is the UK's leading water, energy, environmental, land and sustainable business exhibition and we started going years ago. For us, this is a great opportunity to meet old and new business contacts, learn about the latest developments from other service and product providers in the industry, and of course get everyone excited about the benefits we provide to companies looking to transform their relationship to carbon.
If you're at Sustainability Live! this week you can find us on stand S15.
Next week, from 30th May - 1st June, I'll be in Koln (aka Cologne), Germany with some of my colleagues to attend Carbon Expo 2012. Carbon Expo is the big daddy of business-focused climate change conferences. This year it is taking place just down the road (figuratively speaking) and one week after the policy-focused (and controversy-filled) United Nations Bonn Climate Change Conference. The policy decisions resulting from the Bonn Conference will ultimately affect companies that participate in the EU ETS, the evolution of compliance markets in other countries, and the voluntary carbon market. As a result, I expect some lively discussions at Koln in the wake of that event!
Carbon Clear is a major sponsor of the 2012 State of the Voluntary Carbon Market report, published annually by Ecosystem Marketplace. "The State of" report is the most widely read voluntary carbon market publication and the 2012 edition will be launched at Carbon Expo on May 31. We'll be there for the side event marking the launch, and will have copies of this important report available on our stand immediately after the launch.
You can find us at Carbon Expo on stand B057.
If you're attending any of these events, be sure to come over and visit us. If not, you can always contact our team via the Carbon Clear website.
Labels:
business,
carbon reduction,
climate change,
sustainability
Monday, 14 May 2012
Raising the Speed Limit - Not the Solution the UK Needs
The UK Government is set to announce a consultation about increasing the highway speed limit to 80 miles per hour. The idea, first floated last September, is meant to contribute to economic growth by reducing losses associated with time spent behind the wheel. The main justification given by Government ministers for this proposal is that vehicles are much safer than they used to be, more than offsetting any increased safety risk
This is a very curious argument from a government representative, but it's largely beside the point. Speed limits didn't drop in the U.S. and UK because of safety concerns. They dropped so that those economies could save fuel, and so that motorists could save money. While road safety advocates can argue the case for and against a higher motorway speed limit, we'll focus on the carbon impact.
As the graph above indicates, higher speeds generally translate into greater fuel consumption, and thus greater greenhouse gas emissions. This result should be obvious to anyone who has stuck his or her hand out of the window of a moving car. 40% of a car's fuel is used at highway speeds simply to push air out of the way, and the amount of power required to overcome wind resistance increases along the cube of the velocity. In other words, driving 14% faster (from 70mph to 80mph) will result in much more than a 14% increase in fuel consumption - the actual figure is closer to 20%. This is bad news for companies and individuals looking to reduce their carbon footprints.
Airlines around the world have already put the Government's claims to the test. They have tested their customer base and determined that, within limits, fuel savings trump faster arrival times. Indeed, commercial airliners have been flying 10 mph slower since 2008 in an effort to save fuel. In the U.S., JetBlue has added two minutes to each flight, saving over $13 million a year on jet fuel.
Even this superficial analysis shows that cutting carbon and saving money go hand-in-hand. Money saved on fuel can go into hiring staff, purchasing goods and services, and making productive investments. Increasing the speed limit seems like a very curious way to help the economy.
This is a very curious argument from a government representative, but it's largely beside the point. Speed limits didn't drop in the U.S. and UK because of safety concerns. They dropped so that those economies could save fuel, and so that motorists could save money. While road safety advocates can argue the case for and against a higher motorway speed limit, we'll focus on the carbon impact.
As the graph above indicates, higher speeds generally translate into greater fuel consumption, and thus greater greenhouse gas emissions. This result should be obvious to anyone who has stuck his or her hand out of the window of a moving car. 40% of a car's fuel is used at highway speeds simply to push air out of the way, and the amount of power required to overcome wind resistance increases along the cube of the velocity. In other words, driving 14% faster (from 70mph to 80mph) will result in much more than a 14% increase in fuel consumption - the actual figure is closer to 20%. This is bad news for companies and individuals looking to reduce their carbon footprints.
Airlines around the world have already put the Government's claims to the test. They have tested their customer base and determined that, within limits, fuel savings trump faster arrival times. Indeed, commercial airliners have been flying 10 mph slower since 2008 in an effort to save fuel. In the U.S., JetBlue has added two minutes to each flight, saving over $13 million a year on jet fuel.
Even this superficial analysis shows that cutting carbon and saving money go hand-in-hand. Money saved on fuel can go into hiring staff, purchasing goods and services, and making productive investments. Increasing the speed limit seems like a very curious way to help the economy.
Friday, 11 May 2012
UK Public Wants Corporate Climate Disclosure
First the USA, now the UK. Yesterday the Aldersgate Group reported the results of a poll showing that over three-quarter of the British public supports mandatory carbon reporting by large companies.
These findings come at an interesting time in the debate about support for climate change action. As I mentioned in a post a few months ago, renewable energy feed-in tariff (FiT) levels have been slashed in recent months, resulting in a marked drop in new PV system installations across the UK. Now there is concern that Government support for the Green Deal, an initiative to finance building efficiency retrofits, is wavering.
Companies, meanwhile, are beginning to demand more from their climate change initiatives. It is not enough anymore to buy a few credits, declare oneself carbon neutral and post a certificate on the wall. Company directors now want to understand the business case for tackling climate change, and are under increasing pressure to document the financial return from these measures.
The Aldersgate Group/ Populus poll helps provide this ammunition.
While 77% of the general population believes businesses should face mandatory carbon reporting, the figure jumps to 84% for the desirable 18-44 year-old age group. It is this age group that comprises the target market for most consumer-facing brands. This age group also encompasses the bulk of the working age population, and the overwhelming majority of civic activists.
In other words, the overwhelming majority of customers, employees and potential protesters expect companies to measure and report their greenhouse gas emissions. As Carbon Clear reported last summer, most FTSE 100 companies already disclose the basics of their carbon footprint, but the quality and depth of those reports vary widely. What is more, rates of carbon disclosure and reduction drop off rapidly for companies outside the FTSE 100.
These results are a wake-up call for Britain's corporate sector. In addition to being customers, employees and protesters, many of the people who responded to the Populus poll are also voters. It's reasonable, therefore, to expect the debate about corporate climate change reporting to move up the political agenda and perhaps to result in legislation.
Increased climate change reporting is coming. Companies that take action now to understand their carbon footprint and put in place measures to drive carbon reductions will be best suited to thrive in this new world of carbon disclosure.
These findings come at an interesting time in the debate about support for climate change action. As I mentioned in a post a few months ago, renewable energy feed-in tariff (FiT) levels have been slashed in recent months, resulting in a marked drop in new PV system installations across the UK. Now there is concern that Government support for the Green Deal, an initiative to finance building efficiency retrofits, is wavering.
Companies, meanwhile, are beginning to demand more from their climate change initiatives. It is not enough anymore to buy a few credits, declare oneself carbon neutral and post a certificate on the wall. Company directors now want to understand the business case for tackling climate change, and are under increasing pressure to document the financial return from these measures.
The Aldersgate Group/ Populus poll helps provide this ammunition.
While 77% of the general population believes businesses should face mandatory carbon reporting, the figure jumps to 84% for the desirable 18-44 year-old age group. It is this age group that comprises the target market for most consumer-facing brands. This age group also encompasses the bulk of the working age population, and the overwhelming majority of civic activists.
In other words, the overwhelming majority of customers, employees and potential protesters expect companies to measure and report their greenhouse gas emissions. As Carbon Clear reported last summer, most FTSE 100 companies already disclose the basics of their carbon footprint, but the quality and depth of those reports vary widely. What is more, rates of carbon disclosure and reduction drop off rapidly for companies outside the FTSE 100.
These results are a wake-up call for Britain's corporate sector. In addition to being customers, employees and protesters, many of the people who responded to the Populus poll are also voters. It's reasonable, therefore, to expect the debate about corporate climate change reporting to move up the political agenda and perhaps to result in legislation.
Increased climate change reporting is coming. Companies that take action now to understand their carbon footprint and put in place measures to drive carbon reductions will be best suited to thrive in this new world of carbon disclosure.
Tuesday, 8 May 2012
40% of English Coastline Faces Erosion Risk
Simon Thurley, Chief Executive of English Heritage, wrote a fascinating feature article in the weekend Financial Times about the cost of climate change adaptation. Noting that 1,800 km of the 4,500 km English coast is at risk of erosion, Thurley concedes that the government simply can't afford to save every home and village and that some "will succumb to natural processes and be swept away."
But not all of them. In Walberswick, Suffolk, villagers have formed a trust and plan to raise money to invest in sea defences. In Bawdsey, a charitable trust, local landowners and the council contributed to the development of new houses and used the resulting profits to build a sea barrier to save a historic 19th-century gun platform. Meanwhile, in Dorset, the Landmark Trust spent £889,000 to move Clavell Tower 25 metres inland. These are just a few of the inspiring cases of communities coming together in support of climate change adaptation.
To be fair, Dr. Thurley doesn't call it "climate change adaptation". In fact, he doesn't use phrases like "climate change" or "adaptation" or "global warming" anywhere in his entire 800-word article. This is a surprising omission, when both the UK's Environment Agency and the English Heritage website acknowledge the impact of rising sea levels and more intense storms on the English coast. While some coastal erosion is due to the fact that England is sinking as Scotland continues its post-Ice Age rebound, climate change deserves much of the blame for what is to come.
And while some degree of warming is now locked in - along with the inevitable impacts, it is still not too late to stave off the worst a changing climate holds in store. The 2006 Stern Review and a host of other studies show that it is far more cost effective to mitigate climate change - reduce emissions - than it is to simply continue business as usual an then pay to cope with the consequences.
There is a tremendous amount we can accomplish when we have the will. We can reduce energy consumption, switch to greener sources of energy and less carbon-intensive agricultural practices, and pursue a host of other opportunities to reduce greenhouse gas emissions where we live, work, and play. As Dr. Thurley notes at the end of his article, "I see these measures as inspirational...This is a shift...to the welcome idea that individuals and communities can determine their own destiny."
But not all of them. In Walberswick, Suffolk, villagers have formed a trust and plan to raise money to invest in sea defences. In Bawdsey, a charitable trust, local landowners and the council contributed to the development of new houses and used the resulting profits to build a sea barrier to save a historic 19th-century gun platform. Meanwhile, in Dorset, the Landmark Trust spent £889,000 to move Clavell Tower 25 metres inland. These are just a few of the inspiring cases of communities coming together in support of climate change adaptation.
To be fair, Dr. Thurley doesn't call it "climate change adaptation". In fact, he doesn't use phrases like "climate change" or "adaptation" or "global warming" anywhere in his entire 800-word article. This is a surprising omission, when both the UK's Environment Agency and the English Heritage website acknowledge the impact of rising sea levels and more intense storms on the English coast. While some coastal erosion is due to the fact that England is sinking as Scotland continues its post-Ice Age rebound, climate change deserves much of the blame for what is to come.
And while some degree of warming is now locked in - along with the inevitable impacts, it is still not too late to stave off the worst a changing climate holds in store. The 2006 Stern Review and a host of other studies show that it is far more cost effective to mitigate climate change - reduce emissions - than it is to simply continue business as usual an then pay to cope with the consequences.
There is a tremendous amount we can accomplish when we have the will. We can reduce energy consumption, switch to greener sources of energy and less carbon-intensive agricultural practices, and pursue a host of other opportunities to reduce greenhouse gas emissions where we live, work, and play. As Dr. Thurley notes at the end of his article, "I see these measures as inspirational...This is a shift...to the welcome idea that individuals and communities can determine their own destiny."
Thursday, 3 May 2012
Carbon Capture and Storage: What's the Big Deal?
The U.S. Department of Energy has released the North American Carbon Storage Atlas (NACAS). The atlas is a compendium of geologic sites across Canada, the United States and Mexico where it is theoretically possible to store CO2 produced from stationary sources like power plants, cement factories and the like.
The idea is that this atlas would be used to find and evaluate carbon storage sites close to big greenhouse gas emitters across the continent. This, in turn, would help to improve the economics of carbon capture and storage (CCS) by reducing the logistics costs associated with transporting millions or billions of tonnes of liquified CO2 long distances.
Carbon capture and storage is one of a number of potential tools we can wield in the fight against climate change. The technology has many variants, but the basic approach is to use chemical or mechanical systems to capture CO2 from exhaust gase. Another approach is to chemically remove and capture the CO2 from the fuel before it is burned. In either case, the CO2 is then liquified under pressure, transported to a geologic storage site, and injected into underground basins, where it intended to remain for hundreds of years. After all, CO2 from burning fossil fuels only contributes to global warming if the gas is released to the atmosphere.
NACAS researchers estimate a potential storage capacity of 136 billion tonnes of CO2 in oil and gas fields (where CO2 injection can also release the last remaining oil, which ironically will release more CO2 when burned); 65 billion tonnes in coal fields; and 1.7trillion tonnes in saline reservoirs.
How does that compare to current emissions? In 2010 U.S. greenhouse gas emissions were approximately 6 billion tonnes CO2 equivalent, with 2.25 billion tonnes from electric power plants. So there is enough potential storage in oil, gas and coal fields to storage 88 years of CO2 from power plants, at today's rates of emissions. If coal consumption increased as a result of population growth, economic activity or the lack of viable alternatives, this storage potential would not go as far. And while saline reservoirs have the potential to hold several centuries' worth of CO2, appreciable injection rates can only be achieved at present with hydraulic fracturing (or "fracking"), a process that has caused tremendous concern when used to extract shale gas.
The North American Carbon Storage Atlas therefore serves a useful role in highlighting the theoretical potential of CCS in the fight against climate change. However, it is still not clear whether CCS can play a practical role. One rule of thumb is that commercial-scale CCS would consume approximately 20% of a power plant's output, which means that each unit of electricity sold to end users would be that much more expensive. That figure does not include the cost to transport the liquid CO2 to the injection site and pump it into a storage reservoir 3 kilometers deep. These cost considerations raise doubts about the potential of CCS at a time when wind and other clean energy technologies are falling rapidly in cost, and with governments unable or unwilling to invest billions in pilot schemes to perfect the technology.
The debate over CCS has now shifted to the U.N. Clean Development Mechanism, where proponents are exploring the use of carbon credits sales to help overcome the financial and technical barriers to implementation. Work continues on this front, with the CDM in its CMP 7 report in Durban agreeing to explore ways to develop acceptable rules governing long-term liability, site safety, permanence of the emission reductions, and a host of other issues.
I generally advocate a team approach to carbon reduction, where we pursue multiple emission reduction measures at the same time. However, CCS is potentially so big that, despite its challenges it bears watching closely. Stay tuned.
The idea is that this atlas would be used to find and evaluate carbon storage sites close to big greenhouse gas emitters across the continent. This, in turn, would help to improve the economics of carbon capture and storage (CCS) by reducing the logistics costs associated with transporting millions or billions of tonnes of liquified CO2 long distances.
Carbon capture and storage is one of a number of potential tools we can wield in the fight against climate change. The technology has many variants, but the basic approach is to use chemical or mechanical systems to capture CO2 from exhaust gase. Another approach is to chemically remove and capture the CO2 from the fuel before it is burned. In either case, the CO2 is then liquified under pressure, transported to a geologic storage site, and injected into underground basins, where it intended to remain for hundreds of years. After all, CO2 from burning fossil fuels only contributes to global warming if the gas is released to the atmosphere.
NACAS researchers estimate a potential storage capacity of 136 billion tonnes of CO2 in oil and gas fields (where CO2 injection can also release the last remaining oil, which ironically will release more CO2 when burned); 65 billion tonnes in coal fields; and 1.7trillion tonnes in saline reservoirs.
How does that compare to current emissions? In 2010 U.S. greenhouse gas emissions were approximately 6 billion tonnes CO2 equivalent, with 2.25 billion tonnes from electric power plants. So there is enough potential storage in oil, gas and coal fields to storage 88 years of CO2 from power plants, at today's rates of emissions. If coal consumption increased as a result of population growth, economic activity or the lack of viable alternatives, this storage potential would not go as far. And while saline reservoirs have the potential to hold several centuries' worth of CO2, appreciable injection rates can only be achieved at present with hydraulic fracturing (or "fracking"), a process that has caused tremendous concern when used to extract shale gas.
The North American Carbon Storage Atlas therefore serves a useful role in highlighting the theoretical potential of CCS in the fight against climate change. However, it is still not clear whether CCS can play a practical role. One rule of thumb is that commercial-scale CCS would consume approximately 20% of a power plant's output, which means that each unit of electricity sold to end users would be that much more expensive. That figure does not include the cost to transport the liquid CO2 to the injection site and pump it into a storage reservoir 3 kilometers deep. These cost considerations raise doubts about the potential of CCS at a time when wind and other clean energy technologies are falling rapidly in cost, and with governments unable or unwilling to invest billions in pilot schemes to perfect the technology.
The debate over CCS has now shifted to the U.N. Clean Development Mechanism, where proponents are exploring the use of carbon credits sales to help overcome the financial and technical barriers to implementation. Work continues on this front, with the CDM in its CMP 7 report in Durban agreeing to explore ways to develop acceptable rules governing long-term liability, site safety, permanence of the emission reductions, and a host of other issues.
I generally advocate a team approach to carbon reduction, where we pursue multiple emission reduction measures at the same time. However, CCS is potentially so big that, despite its challenges it bears watching closely. Stay tuned.
Wednesday, 2 May 2012
ICROA's Code of Best Practice
ICROA, or the International Carbon Reduction and Offsetting Alliance, is a self-regulatory industry body established in 2008 by Carbon Clear and seven other reputable carbon offset providers in Europe, the United States and Australia. We came together to promote good practice for offset-inclusive carbon management, and to make sure customers and other stakeholders continue to have confidence in the voluntary carbon market.
It's not easy for a company or non-profit organisation to become an ICROA member. First there are the membership requirements, which include having an established track record delivering carbon management products and services, a minimum annual turnover (revenue) threshold, and checks on the applicant's reputation. Member companies commit to volunteering time and resources to strengthen ICROA and its voluntary carbon market work, which may go beyond their day-to-day commercial activities.
Most importantly, members must comply with ICROA's Code of Best Practice. It is the Code and annual compliance audit that distinguishes ICROA from other membership and lobbying bodies in the carbon market. I have chaired ICROA's Policy Working Group from the beginning and have therefore been intimately involved in the development and implementation of the Code of Practice.
In summary, the ICROA Code of Practice requires members to:
- Measure organisational or product and service carbon footprints to internationally recognised standards like ISO 14064-1, the WRI GHG Protocol, or PAS 2050. Where members do not provide this service themselves, they must ensure that their subcontractors follow these standards;
- Encourage customers to set ambitious greenhouse gas reduction targets and help them identify opportunities to reduce their footprint;
- Help customers achieve zero net carbon emissions for all or part of their footprint via the use of carbon offsets from an ICROA-approved carbon credit standard. Approved standards include American Carbon Registry, CarbonFix, the Verified Carbon Standard, the Climate Action Reserve, the Gold Standard, and of course the Clean Development Mechanism. (The ICROA Policy Working Group takes the lead in evaluating the suitability of carbon credit standards.) Carbon credits must be shown to be real, measurable, permanent, additional, verifiable, and unique.
- Retire carbon offset credits in a traceable independent registry after they have been sold to ensure those offsets are permanently matched against specific customer greenhouse gas emissions.
- Work with customers to ensure they are communicating their carbon footprint, reduction and offset activities accurately.
- Submit to an annual audit and report member compliance (or non-compliance) to the ICROA Secretariat.
I believe the work of ICROA and its members is to some extent responsible for the rapidly growing maturity of the voluntary carbon market. We are regularly approached by carbon offset providers who wish to become members, and push them to demonstrate good practice. Even more interestingly, the carbon credit standards themselves often approach ICROA to be evaluated and added to the approved list. A final proof point: last year, ICROA merged with the International Emissions Trading Association (IETA), in recognition of the growing importance of the voluntary carbon market.
Indeed, I don't think it would be a huge stretch to claim that ICROA and its members have helped to keep the voluntary carbon market buoyant even as the compliance market struggles with depressed prices and reduced demand for credits. As I noted a few days ago, customers in the voluntary carbon market offset for a variety of reasons, but the environmental integrity of the carbon offset process is key to the buying decision.
No one enjoys an audit, but the knowledge that this annual process helps to strengthen the carbon market and reassures our customers makes the ICROA compliance audit that much more bearable.
Subscribe to:
Posts (Atom)